Invoice Finance and Business Loans are two common ways Australian small and medium-sized enterprises (SMEs) access working capital. Both can fund your business, but they work in very different ways and suit different needs. Find out more about ScotPac’s Invoice Finance offering.
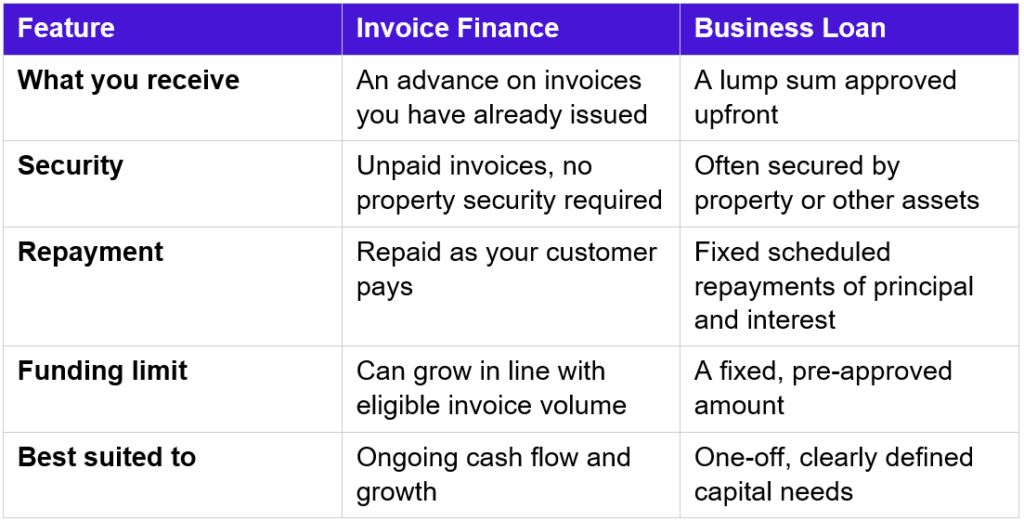
In short, Invoice Finance, also known as Debtor Finance, lets you unlock cash tied up in unpaid invoices. Your unpaid invoices are used as security, so there is generally no need for property security, and the facility is repaid as your customers pay. This can make it well suited to ongoing cash flow needs and growth.
A Business Loan works differently. It usually provides a lump sum that you repay over a set term with scheduled instalments of principal and interest. It may require security, and it can suit a one-off, clearly defined need.
So which should you choose? It often comes down to one question. If your challenge is the gap between doing the work and getting paid, Invoice Finance tends to be the more practical fit. If you need a fixed sum for a specific purpose, a Business Loan may serve you better. Many businesses use both.
Why do Australian SMEs weigh Invoice Finance against a Business Loan?
It usually starts with a cash flow gap. You have delivered the work and issued the invoice, and then you wait. Standard trade terms of 30, 60 or even 90 days mean the money you have already earned can sit out of reach for months.
In the meantime, wages, suppliers and overheads do not wait. And when the bank’s answer is a slow application or a request for property as security, many business owners start looking for something faster and more flexible.
Understanding how these two options differ is the right place to start.
What is Invoice Finance, and how does it work for Australian SMEs?
Invoice Finance lets your business access the value of unpaid sales invoices before your customers pay them. The facility is secured against your receivables, rather than your property or other business assets.
How does Invoice Finance work?
- You issue invoices to your customers as normal.
- Your lender, such as ScotPac, advances you a percentage of the invoice value.
- You receive the funds, often in as little as 24 hours once your facility is approved and set up.
- When your customer pays, you receive the remaining balance, less applicable fees.
Advance rates depend on the product. Generally, Invoice Finance facilities allow to release up to 85% of eligible invoice value. Because it is a revolving facility, your available funding can grow as your sales do, and there are no fixed monthly repayments in the same way as a term loan. The facility is repaid as your customers pay.
Which businesses does Invoice Finance suit?
Invoice Finance is designed for business-to-business (B2B) companies that sell on trade terms and feel the strain of slow-paying customers.
It is particularly useful for businesses growing quickly, where every new contract widens the gap between doing the work and being paid for it. Transport, recruitment, manufacturing and wholesale businesses all rely on it heavily.
What is a Business Loan, and how does it work?
A Business Loan is provided by a bank or another lender as a lump sum that is repaid over time. It can fund a wide range of needs, from buying equipment or premises to refinancing debt or funding an acquisition.
How does a Business Loan work?
- You apply for a set amount and outline how you will use it.
- Once approved, you receive the loan funds.
- You make scheduled repayments of principal and interest until the loan is repaid.
- Most Business Loans require some form of security to support the facility.
ScotPac offers tailored business lending alongside its working capital solutions. You can explore ScotPac’s Business Loan options here.
Which businesses does a Business Loan suit?
A Business Loan suits a defined, one-off need where you know how much you require and over what period you can repay it.
Buying a specific asset, funding a planned expansion or consolidating existing debt are good examples, where the certainty of a fixed sum and fixed schedule can be useful.
Invoice Finance vs a Business Loan: what’s the real difference?
Here’s how the two compare across the factors that matter most to Australian SMEs.
Is Invoice Finance a good idea, or should you choose a Business Loan?
Neither option will be right for every business. It depends on the challenge in front of you.
Invoice Finance tends to suit businesses whose revenue is healthy but tied up in unpaid invoices, who want funding that can scale with growth, and who would rather not pledge property as security.
A Business Loan makes more sense when you need a specific sum for a specific purpose and can plan comfortably around fixed repayments.
There is also no rule that says you must choose only one. Many businesses use Invoice Finance for everyday cash flow and a Business Loan for a defined investment.
Not sure which fits your situation? Compare your options with a ScotPac lending specialist and we can help you weigh up the right approach for your business.